- SPECIMEN
Waterlily
- FILED AS
AI estimate of when your long-term care starts and what it costs, plus a shareable plan
- INTAKE DATE
- 2026-09-27
- CLASS
- Analytics
- METHOD
- 1 page scraped, 3 search passes, 10 community sources
Koda Score = weighted blend: capability 35, ease 20, value 25, momentum 20.
The scope is narrow and the model is unexplained, which caps capability; the form-to-email flow and a $0 or $9.99/year price make ease and value strong; press recognition in 2026 is offset by almost no independent user discussion.
6 MIN READA free intake form that returns a projected care timeline and cost range is the cheapest way to start the hardest money conversation a family has, and the $9.99 yearly plan is close to a rounding error. Adult children of aging parents and advisors who need a concrete starting point should run it now. Nobody should treat the output as a funding decision until an advisor checks it against real savings and coverage, because Waterlily's homepage does not explain how its projections are built.
Medicare will not fully cover long-term care, and Waterlily will email you a free projection of when that bill is likely to start and roughly how large it gets.
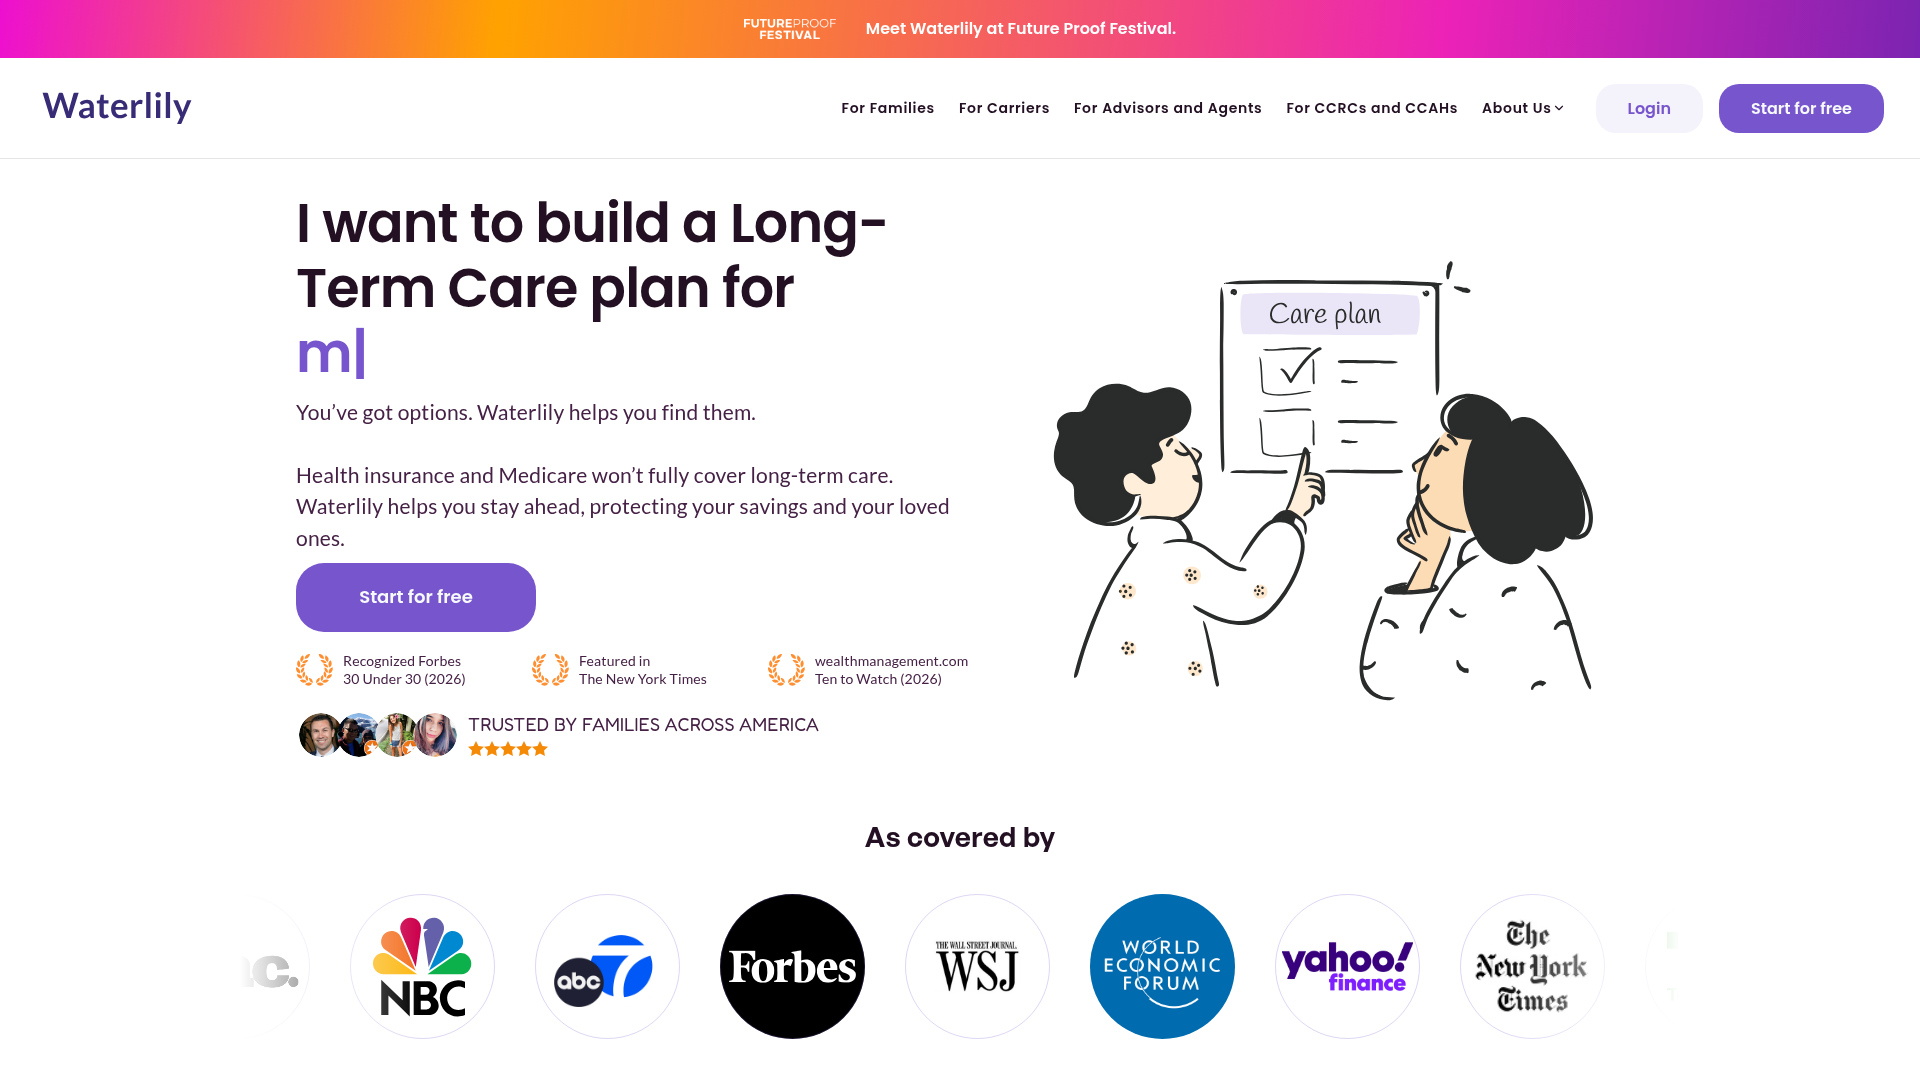
Captured: www.waterlily.com on 2026-09-27.
The short version.
4 LINESThe free tier emails you an expected care timeline and cost insights after a secure intake form.
$9.99 per year adds a personalized care plan you can share with family or advisors and update over time.
Waterlily states it is HIPAA compliant and SOC 2 certified, which matters for a form full of health details.
Use the projection to open the family conversation early, then have an advisor test it against your actual savings and insurance.
What it actually does.
7 CAPABILITIES- AI care projections
- Estimates when long-term care is likely to begin and what it may cost, based on your intake answers.
- Free results by email
- The timeline and cost insights land in your inbox at no charge, so you can judge the output before paying.
- Personalized care plan
- The subscription turns the projection into a step-by-step plan built around your situation.
- Sharing with family or advisors
- Send the plan to relatives or a financial advisor so everyone works from the same numbers.
- Updates over time
- Revise the plan as health or finances change, which keeps the numbers from going stale.
- HIPAA and SOC 2
- Waterlily states it is HIPAA compliant and SOC 2 certified for the health data you enter.
- Web and mobile
- The form and plan are available on web and mobile, and the form can be completed at your own pace.
How you would actually use it.
3 PLAYS- The free gut check
- Run the free intake for one parent before spending a cent and read the emailed timeline cold. If the projected start date lands sooner than anyone in the family assumed, that surprise is your reason to pay $9.99 and build the plan.WHOAdult child worried about a parentPAYOFFA zero-cost read on whether the family is behind, with a clear trigger for going further.
- Pre-meeting homework
- Ask clients to complete the form and share their care plan with you ahead of the annual review. Spend the meeting comparing the projected cost range to their actual savings and insurance.WHOFinancial advisorPAYOFFReview time goes to the funding gap, and the client arrives already primed on the long-term care topic.
- The update trigger
- Set one standing rule: any new diagnosis, move, or change in savings means someone updates the plan and re-shares it with the whole family.WHOFamily caregiver coordinating siblingsPAYOFFThe shared plan stays current, and nobody argues from an outdated number.
Pricing, straight.
2 TIERS- Verdict on the price
- $9.99 a year is trivially cheap for a shareable care plan, and the free estimate lets you judge the output before you spend anything.
What people online are saying.
0 QUOTEDIndependent public discussion of Waterlily's care planning tool is essentially absent so far; the only praise appears as testimonials on Waterlily's own site, and most Reddit chatter under the name is about an unrelated romance story.
The honest part.
5 LIMITATIONSThe homepage does not explain how the AI projections are calculated, so you cannot audit the assumptions behind the timeline or cost range.
Waterlily notes the plan may not cover every long-term care related cost, so treat the range as a floor for discussion.
No enterprise or group pricing is listed, which leaves employers and large advisory firms without a published option.
Integrations are described only as unnamed top insurance carriers and advisory institutions, with no detail on what connects to what.
There are no independent user reviews to check the testimonials against, and searching the name mostly surfaces a romance story, a turbine charger, and a pond plant.
The field.
2 ALTERNATIVES- Genworth Cost of Care and CareScout tools
- Insurance-backed long-term care cost data and research tools.PICK IT WHENYou want to look up care costs by region and service type yourself, without building a personal plan.
- Advisor-led manual modeling
- A long-term care specialist or financial advisor building projections in their own spreadsheets or planning software.PICK IT WHENYour situation is complex enough that you want a human to own every assumption, and you are willing to pay advisory fees for it.
Getting started.
3 STEPSClick Start for free and complete the secure intake form at your own pace.
Read the expected care timeline and cost insights sent to your email.
Subscribe for $9.99/year to build the care plan and share it with family or your advisor.
Quick answers.
3 ANSWERS- Is the free version enough on its own?
- It gives you the core output: an expected care timeline and cost insights by email. Building a care plan, sharing it, and updating it later require the $9.99/year subscription.
- Is it safe to enter my health details?
- Waterlily states it is HIPAA compliant and SOC 2 certified. Those are the standard assurances to look for with health data, though the certifications themselves are the only detail it publishes on the homepage.
- Can I use the numbers to decide on long-term care insurance?
- Use them to frame the decision. Waterlily says the plan may not cover every related cost and does not explain its methodology on the homepage, so have a financial advisor check the projection against your actual savings and insurance before you buy anything.
The bottom line.
SPECIMEN 0234 CLOSEDFill out the free form this week and read what comes back. Then put the number in front of the people who control the money: your family and your advisor.
Field research: 1 page scraped · 3 search passes · 10 community sources. Reviewed by the Koda desk on 2026-09-27.